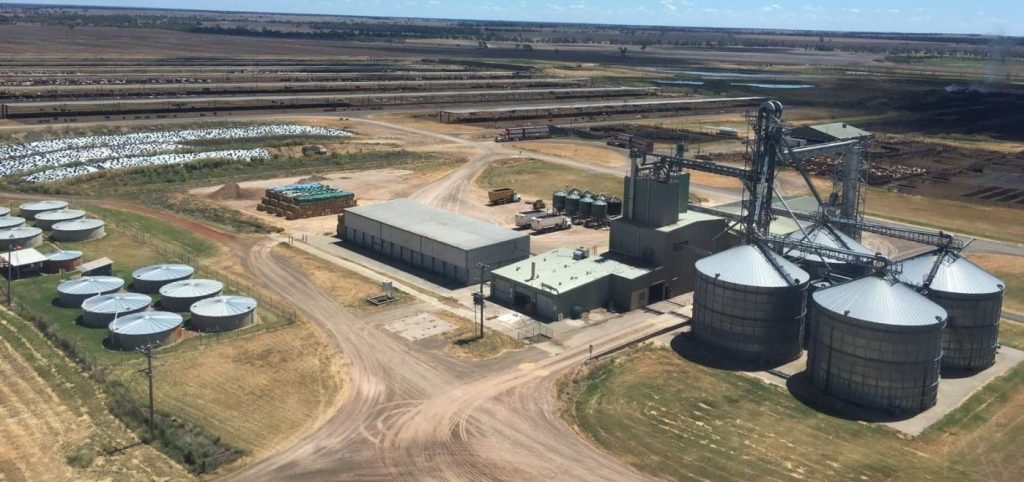
Bindaree’s Myola feedlot near North Star in Northern NSW
AUSTRALIA’S grainfeeding sector has been identified as the standout performer across the rural property market over the past 12 to 18 months, recording the highest volume of transactions in more than three decades and a dramatic escalation in asset values.
Valuer Tim Bartholomew, who works with Toowoomba-based Valcore, said traditionally, feedlots are bought and sold on a dollars-per-Standard Cattle Unit ($/SCU) basis.
Tim Bartholomew
“This metric excludes the underlying grazing land and non-feedlot improvements, but includes the feedlot infrastructure itself, such as cattle pens, feed mills, commodity storage sheds, workshops, weighbridges, offices and processing facilities,” he said.
Reliable water is also incorporated within this assessment, typically at a benchmark allowance of 24ML per 1000 SCU, Mr Bartholomew said.
He said the current wave of transactions had included several of Australia’s best-known feeding operations, including Killara, Rangers Valley, Smithfield, Yarranbrook, Vandyke, Pinegrove and Lloyd’s Feedlot.
Purchasers had largely comprised established feedlot operators and large corporate-scale grazing enterprises seeking to secure value-adding opportunities and capitalise on continuing demand for grainfed beef production.
Analysis of recent sales by Mr Bartholomew indicates feedlot values ranging from about $2200/SCU to more than $3000/SCU, depending on factors such as location, scale, age, condition and milling infrastructure.
He said premiums were increasingly being paid for operations incorporating more advanced feed processing systems, particularly steam flaking technology, compared with traditional dry or wet rolling systems.
Two significant feedlots currently being offered to the market – Mort & Co’s Grassdale near Dalby and Bindaree Beef’s Myola feedlot near Moree – are expected to provide further insight into current investor sentiment.
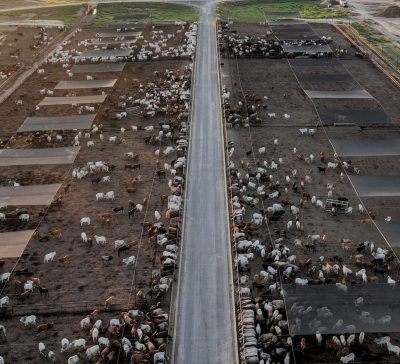
Cattle on feed at Grassdale
“Should transactions occur, values achieved are likely to be consistent with, or potentially exceed, recent benchmarks,” Mr Bartholomew said.
He said the marketing of Myola presented an additional point of interest, with the property being offered subject to a leaseback arrangement.
“The structure and terms of any lease agreement may influence both the purchaser profile and ultimate sale price.”
He said the magnitude of the sector’s value growth becomes apparent when viewed through a historical lens.
“Myola reportedly sold in 2015 for around $850/SCU, while Vandyke changed hands in 2021 at a similar level. Current evidence indicates values have more than doubled over that period.”
Water entitlements follow feedlot expansion
The strong performance of the feedlot sector has also flowed through to the market for secure stock-intensive water entitlements sourced from the Great Artesian Basin in southern Queensland.
Mr Bartholomew said demand generated by feedlot expansion had driven a remarkable increase in values for water allocations within the Gubberamunda Aquifer.
“Market evidence indicates entitlement values have risen from around $3000/ML in 2019 to approximately $7000/ML in 2021,” he said.
“The most recent confirmed transaction reportedly achieved $25,000/ML in 2025, while industry sources have cited an unconfirmed sale at approximately $38,000/ML during 2026.”
Mr Bartholomew said industry participants reported the market remains undersupplied, with some buyers prepared to pay substantially higher figures for strategically located and secure allocations.
“Queensland Water Consultants have indicated purchaser demand at levels of up to $50,000/ML.”
“At current confirmed market levels of around $25,000/ML, the water component alone equates to around $600/SCU based on the industry’s benchmark water requirement of 24ML per 1000 SCU,” Mr Bartholomew said.
He said this highlighted the increasingly significant contribution water security makes to overall feedlot asset values and reinforces its status as a critical factor in future feedlot development and expansion.
Outlook
Mr Bartholomew said the convergence of strong grainfed beef demand, ongoing industry consolidation, limited availability of large-scale feedlot assets and escalating water entitlement values has created a highly competitive investment environment.
“With several major grainfed operations either recently sold or currently being marketed, the sector appears to be establishing a new valuation benchmark.”
“The results achieved by Grassdale and Myola will be closely watched by investors, operators and valuers alike as indicators of where the market heads next,” Mr Bartholomew said.
HAVE YOUR SAY